12/20/2014 - Financial Repression Banks Remove the “Heart” of Dodd-Frank
6 years of highly visible Dodd-Frank legislation and thousands of lines of regulation, with no public debate, was just quietly removed and “neutered” by the stealth of an “Ear-Mark”.
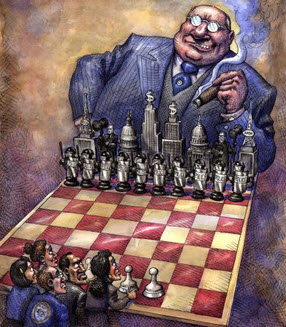
To maintain government financing the banks have held Washington hostage.
Maintain our profit margins and have the public accept the risk of $3003 TRILLION or….. else!
The Bill (yet another ‘Ear-Mark’) allows financial institutions to trade certain financial derivatives from subsidiaries that are insured by the Federal Deposit Insurance Corp. — potentially putting taxpayers on the hook for losses caused by the risky contracts. Big Wall Street banks had typically traded derivatives from these FDIC-backed units, but the 2010 Dodd-Frank financial reform law required them to move many of the transactions to other subsidiaries that are not insured by taxpayers.
“It is because there is a lot of money at stake,” Johnson said. “They want to be able to take big risks where they get the upside and the taxpayer gets the potential downside,”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/20/2014 - Financial Repression: Energy Company Debt Fallout from Federal Reserve Financial Repression Policies
Bloomberg reports on the unfolding fallout now happening in energy-company debt as a result of Federal Reserve financial repression policies of zero interest rates & stimulus-induced asset inflation .. “Since early 2010, energy producers have raised $550 billion of new bonds and loans as the Federal Reserve held borrowing costs near zero, according to Deutsche Bank AG. With oil prices plunging, investors are questioning the ability of some issuers to meet their debt obligations. Research firm CreditSights Inc. predicts the default rate for energy junk bonds will double to 8% next year .. ‘Anything that becomes a mania — it ends badly .. And this is a mania.'” .. The Fed’s decision to keep benchmark interest rates at record lows .. has encouraged investors to funnel cash into speculative-grade securities to generate returns, raising concern that risks were being overlooked.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/20/2014 - Financial Repression Creating System Bias and Noise
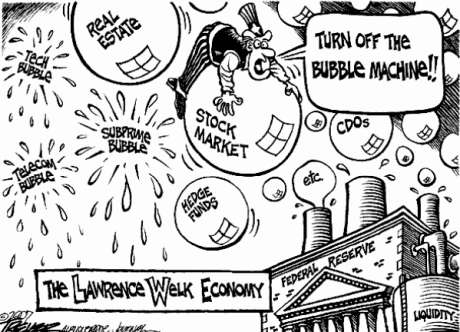
“The current capitalism suffocating regime of Keynesian central banking and extreme financial repression has created systematic bias and noise .. These distortions are the result of mis-allocations and malinvestments reflecting artificial sub-economic costs of debt and capital. The resulting bubbles and booms, in turn, cause highly aggregated measures of economic activity to be flattered by the unsustainable production, spending and investment trends underneath at the sector level .. Bubble finance does not create growth; it funds phony booms that end up as destructive round trips .. The meaning of the oil crash is that the central bank fueled bubble of this century is over and done. We are now entering an age of global cooling, drastic industrial deflation, serial bubble blow-ups and faltering corporate profits.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/13/2014 - Iceland Plans to Impose a 25-40% Exit Tax on all Assets Leaving the Country
Bloomberg & Morgunbladid report that Iceland plans to impose an exit tax as part of removing its capital controls – all bank assets would be subject to the levy .. more financial repression .. “Representatives from Iceland’s government, central bank and parliament discussed imposing a tax as high as 40% on investors exiting the island.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/12/2014 - Financial Repression Has Caused Drastic Mispricing of Financial Assets
“There are financial time bombs planted everywhere in the world economy because central bank financial repression has caused drastic mispricing of nearly every class of financial asset, which is to say, every layer of collateral which has ratcheted-up the entire edifice .. This drastic central bank driven financial repression has unleashed a mindless pursuit of ‘yield’ or short-term trading gains that give the concept of ‘irrational exuberance’ an entirely new definition .. What is happening now is that risk is coming out of hiding; the collateral chains are buckling; the financial time bombs are beginning to explode. There is nothing especially new about this development—its the third occurrence this century. But there is possibly something different this time around the block. This time the carnage could be much worse because the most recent tsunami of central bank credit was orders of magnitude larger and more virulent than during the run-up to the Lehman event or the dotcom implosion. Moreover, the central banks are now out of dry powder—– impaled on the zero-bound. That means any resort to a massive new round of money printing can not be disguised as an effort to ‘stimulate’ the macro-economy by temporarily driving interest rates to ‘extraordinarily’ low levels. They are already there. So duck and cover. This storm could be a monster.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/11/2014 - Moody’s and S&P Warn That European Banks Are At Risk Of Bailins in 2015
GoldCore article on recent developments relating to bailins & financial repression .. Banks in most western nations are vulnerable to bail-ins in 2015 & the recent G20 meeting in Brisbane was a further move towards the stealth bail-in regimes .. S&P Managing Director Stefan Best: “The European bail-in tool decreases the predictability of state support.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/10/2014 - David Stockman on how Negative Interest Rates are taking away Wealth from Bank Depositors
TomWoodsTV interviews David Stockman .. Stockman says the Keynesians have had their day in Japan & worldwide .. rails against Harvard University’s Ken Rogoff on the abolition of physical cash to facilitate the further expansion of monetary policy – governments trying to implement negative nominal real interest rates to take wealth away from bank depositors to help pay down government debt .. it’s financial repression .. 30 minutes
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/10/2014 - Financial Repression: Negative Interest Rates Are Coming To U.S. Banks
The WSJ reports that big U.S. banks – primarily of the TBTF variety – “are urging some of their largest customers in the U.S. to take their cash elsewhere or be slapped with fees, citing new regulations that make it onerous for them to hold certain deposits.” .. The banks, including J.P. Morgan Chase & Co., Citigroup Inc., HSBC Holdings PLC, Deutsche Bank AG and Bank of America Corp. , have spoken privately with clients in recent months to tell them that the new regulations are making some deposits less profitable .. “In some cases, the banks have told clients, which range from large companies to hedge funds, insurers and smaller banks, that they will begin charging fees on accounts that have been free for big customers, the people said. Bank officials are also working with these firms to find alternatives for some of their deposits, they said .. J.P. Morgan told some clients of its commercial bank recently that it would begin charging monthly fees on deposit accounts from which clients can withdraw money at any time. The new charges will start Jan. 1 for U.S. accounts, according to an Oct. 21 memo reviewed by the Journal, and later for international accounts.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/09/2014 - Financial Repression: Banks Being Setup To Confiscate Bank Deposits & Other Assets in the Next Banking Crisis
Interview with Attorney Ellen Brown .. explains recent developments in regulations & G20 initiatives on bank BailIns, a form of financial repression in which banks are being setup to confiscate bank deposits & other assets in the event of a banking crisis .. “The banks will say, well, we don’t have it. All the money goes into one big pool since Glass Steagall was repealed. They are allowed to gamble with that money and that’s what they do. I think maybe Bank of America is the most vulnerable because of Merrill Lynch. Everybody is concerned, and they do very risky deals and they are on the edge. I think they have over $50 trillion in derivatives and over $1 trillion in deposits. . . The Dodd-Frank Act says we, the people, are no longer going to be responsible for the big banks when they collapse. It is not clear the FDIC will even be able to borrow from the Treasury, but even if they could, who is going to pay that money back? Let’s say they borrowed $1 trillion. Who is going to pay that $1 trillion dollars back? It will bankrupt all the small banks that had to contribute to this premium. They will say we’re raising your premium to everything you got, basically. Little banks will go out of business, and who is going to survive–the big banks. . . . What we’re going to have left is five big banks, and everybody else is going to be bankrupt.” .. The G-20 met recently in Australia to make new banking rules for the next financial calamity, Brown explains how these new rules will allow banks to take money from depositors & pensioners worldwide: “It became rules we agreed to actually implement. There was no treaty, and Congress didn’t agree to all this. They use words so that it’s not obvious to tell what they have done, but what they did was say, basically, that we, the governments, are no longer going to be responsible for bailing out the big banks. These are about 30 international banks. So, you are going to have to save yourselves, and the way you are going to have to do it is by bailing in the money of your creditors. The largest class of creditors of any bank is the depositors .. Theoretically, we are protected by deposit insurance up to $250,000 in the U.S. and 100,000 euros in Europe. The FDIC fund has $46 billion, the last time I looked, to cover $4.5 trillion worth of deposits. So, even though we are protected by the FDIC, the FDIC is not going to have the money. . . . This makes it legal for these big 30 banks to take our money when they become insolvent. They are too-big-to-fail. This was supposed to avoid too-big-to-fail, but what it does is institutionalizes too-big-to-fail. They are not going to go down. They are going to take our money instead.” .. 22 minutes
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/08/2014 - IMF Needs To Authorize Itself To Have Zero or Negative Interest Rates
IMF Paper proposes changes to its authority to ensure it is authorized & capable of handling negative interest rates .. “There is no authority under the Articles of Agreement for the Fund to establish a zero or negative SDRinterest rate .. This paper proposes technical amendments .. and the burden sharing mechanism to address these issues.” .. IMF preparing financial repression on interest rates.
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
“I think that the reason bankers and governments dislike gold backed hard currencies is that it limits their ability to devalue their fiat currency and redistribute wealth in order to stay in power. The governmental solution to all the debt in the world is to try to inflate it away and slowly take money away from the people via currency depreciation and manipulating interest rates so savers and forced owners of government debt (such as pension schemes) make a negative return .. The market is not free, it is controlled .. A move away from fiat currency and back to using gold backed currency would remove the ability of governments to print money and this in turn would remove their ability constantly try to avoid facing the consequences of building up huge debts, which in term means they would have to face the music and actually have a plan to repay it .. It is the central banks and private banks who are complicit in this government sponsored process .. I am getting pretty fed up with having my savings earning no interest and possibly being devalued and of not being able to find any sensible place to invest my hard earned money due to central bank policies making it impossible to make any return anywhere without taking crazy risks.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/05/2014 - New G20 Rules on Financial Repression
Ellen Brown highlights the results of the recent G20 meeting in Australia, a meeting which Russell Napier called “the day money died” – the day deposits died as money .. Napier: deposits are now just part of the commercial banks’ capital structure, which means they can be “bailed-in” or confiscated to save the banks .. the new rules include derivatives, stipulating a priority of payment of banks’ derivative obligations ahead of everyone else in the event of a crisis .. Brown points out “everyone else” includes pension funds .. “‘Bail in’ has been sold as avoiding future government bailouts and eliminating too big to fail (TBTF). But it actually institutionalizes TBTF, since the big banks are kept in business by expropriating the funds of their creditors.” .. the new G20 rules being implemented emphasize turning bank liabilities into capital, with liabilities including “unsecured debt” like bank deposits .. Brown says banks are now offering “bailinable bonds” which convert into bank capital in the event of a bank crisis – pension funds are now buying these types of bonds in seeking yield sufficient to meet their pension obligations, but a recent policy brief by the Peterson Institute for International Economics calls “bailinable securities” fool’s gold that woud save banks at the expense of pensioners in the event of a bank crisis .. so investors, individuals, pensioners, savers & retirees are now at risk of confiscatory bail-ins to help keep too big to fail banks in business.
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
12/04/2014 - Central Banks and Financial Repression
“Central banks would like to escalate their devastating war on savers by driving interest rates even deeper into negative nominal and real territory. But they are now stymied for two reasons .. In the case of their preferred route of driving ‘real’ interest rates more deeply into negative returns by cranking up consumer inflation, they are blocked by economic reality. Households are still buried in debt and can no longer borrow, spend and ratchet-up their balance sheet leverage ratios as they did in the 40 years preceding the financial crisis. Likewise, a deflationary global economy— drowning in the excess industrial capacity and malinvestments that have been generated by nearly two decades of worldwide financial repression—– keeps a tight lid on the price of consumer goods. So the tried and true route of inflating governments out of their debt obligations has been precluded .. At the same time, interest rates are already at the zero bound in nominal rate terms, meaning that only significantly negative nominal rates can further reduce the burden of public debt. However, even central bankers are smart enough to realize that if the monetary and fiscal authorities of the state go too far in imposing negative rates on bank deposits or in threatening to ‘bail-in’ depositors, they could incite a run on the bank.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
11/30/2014 - Financial Repression: Distorting and Inflating Asset Prices
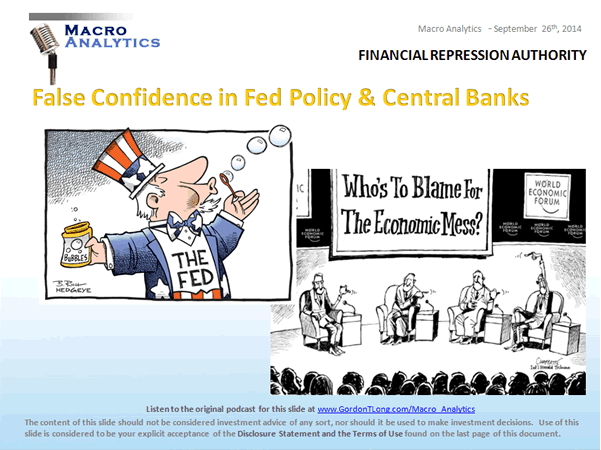
“The purpose of central bank financial repression and ZIRP is to distort and inflate asset prices. Our monetary politburo even admits that it is in the monetary scam business via its self-serving doctrine called ‘wealth effects’ .. The game here is to drive the stock market averages ever higher through massive liquidity injections into the Wall Street dealer markets. This purportedly causes people to feel richer and to spend and invest more, creating a virtuous circle of prosperity, world without end .. We know by now, however, that ‘wealth effects’ money printing does not help the main street economy. And while it does produce awesome financial market gains—–these turn out to be unsustainable bubbles that inexorably crash .. The resulting financial bubbles have been global in scope .. The true nature of today’s Keynesian central banking – The actual impact of the current ‘wealth effects’ regime is not economic growth and rising profits, but, instead, a vast inflation of financial assets.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
11/29/2014 - Financial Repression: Negative “Real” Rates are the Norm
Article highlights how a number of banks are charging institutional clients for depositing their funds, meaning the interest rates are negative .. Several banks, including Bank of New York Mellon Corp, Credit Suisse Group AG, Goldman Sachs Group Inc & JP Morgan Chase & Co., have applied this practice .. “Investors and corporations, along with investment funds and asset managers, are becoming the biggest victims of this practice. They view this change as revolutionary. Multinational organizations that manage large-scale operations in the continent are witnessing a spike in their expenses as a result of this practice. Fear of a doomed European financial system is one of the driving forces behind such drastic measures. Currently, the economy is at a halt and in desperate need for households and businesses to add money in the system and revive confidence in investors .. This might lead to abandoned clients looking for more secure options to place their misplaced money or force them to opt for high-risk instruments such as debt-based funds or repurchase agreements.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
11/28/2014 - Tim Price On Financial Repression
Article & interview on perspective by Tim Price on financial repression insight on UK Tip TV .. Rather than saving the global economy, very low interest rates are a ’coiled spring’ for trouble ahead .. very low interest rates are implementing financial repression, which involves deliberately holding down interest rates below inflation & keeping government borrowing costs low .. “People are piling into stocks because they’ve frankly got no other choice, but I think we’ve seen how this film ends.” .. Price thinks that investing in Asia is the best bet to deal in this environment.
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
11/27/2014 - The Consequences of Imposing Negative Interest Rates
Pater Tenebrarum essay on the adverse unintended consequences of banks imposing negative interest rates on deposits, all a result of financial repression .. he points out how banks have recently started to charge interest on bank deposits in Germany, & now banks elsewhere are doing the same: “Other banks were presumably watching to see if depositors would flee, and when that didn’t happen, Commerzbank decided to go down the same road.” .. the essay quotes Austrian School Economist Ludwig von Mises on what happens when interest payments are abolished or go negative – owners of capital will begin to consume their capital & society will become impoverished: “.. there cannot be any question of abolishing interest by any institutions, laws, and devices of bank manipulation. What can be abolished by laws and decrees is merely the right of the capitalists to receive interest. But such laws would bring about capital consumption and would very soon throw mankind back into the original state of natural poverty.”
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
11/23/2014 - Insight into Financial Repression
Brinker Capital Senior Investment Manager, Jeff Raupp, CFA, provides commentary on the issues surrounding the debt burdens of many developed governments today, how this era of financial repression may impact investors .. 5 minutes
https://youtu.be/xinMULaP-nY
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
11/22/2014 - Low Interest Rates From Financial Repression Means Savers Are Struggling To Save
Article from Korean news source (in English) highlghts how low interest rates mean Koreans are struggling to save .. “Low interest rates on time deposits mean that Koreans can’t save the way they used to .. Until the 1990s, when the average interest rate hovered at around 10%, a common way to build up assets in Korea was to set aside a portion of wages in the bank every month as a time deposit – after a while, you would be able to buy property with the savings .. not any more .. “Korean consumers will have to live with such low-interest bank savings for a substantial period of time as the country’s central bank is likely to keep its benchmark interest rate in response to the continued quantitative easing of major economies like Japan and the European Union.” .. when you take into account the inflation rate in Korea, you have negative real interest rates, characteristic of financial repression.
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.
11/22/2014 - FINANCIAL REPRESSION for DUMMIES
Gordon T. Long has been sounding the alarm on Financial Repression for quite some time. Unfortunately most people have been unaware that their wealth is being stripped away before their very eyes. But Gordon and his associates have devised a number of strategies that can be exercised to avoid this fate. Before you can solve a problem, you’ve got to admit that it exits.
Disclaimer: The views or opinions expressed in this blog post may or may not be representative of the views or opinions of the Financial Repression Authority.


 12/20/2014 - Financial Repression Banks Remove the “Heart” of Dodd-Frank